Korea VAT Filing Schedule 2026: Deadlines for Companies, Individuals, and Simplified Taxpayers
The final VAT return is due July 25 and January 25 of the next year. The preliminary period is April 25 and October 25. Companies file a preliminary return. Individual general taxpayers pay a preliminary notice. If a deadline falls on a holiday, it moves to the next business day.
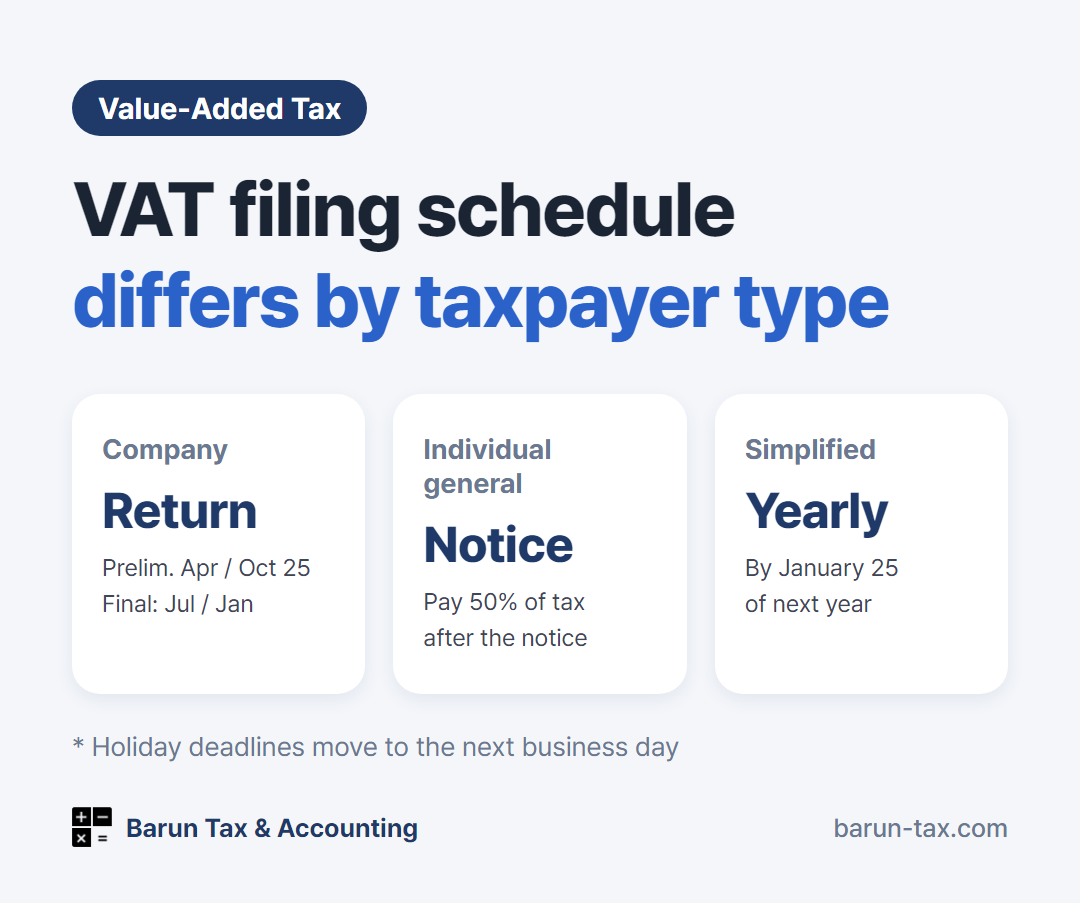
The VAT final return is due July 25 and January 25 of the next year for all taxpayers. In the April 25 and October 25 preliminary periods, companies file a preliminary return and individual general taxpayers pay a preliminary notice. Simplified taxpayers file once a year, by January 25 of the next year. If a deadline falls on a holiday, it moves to the next business day. The second-half 2026 preliminary return is due by October 26.
VAT filing schedule: companies and individual general taxpayers
Each VAT taxable period is split into the first period (January~June) and the second period (July~December). Each of these is split again into the first three months (preliminary) and the last three months (final). The final return deadline is the same for all taxpayers, but whether you file a return or receive a notice in the preliminary period depends on your taxpayer type.
| Date | Period covered | Company | Individual general taxpayer |
|---|---|---|---|
| April 25 | January ~ March | Preliminary return | Pay preliminary notice |
| July 25 | January ~ June | Final return | Final return |
| October 25 | July ~ September | Preliminary return | Pay preliminary notice |
| January 25 of the next year | July ~ December | Final return | Final return |
A company’s final return covers the remaining three months, excluding the three months already filed in the preliminary return. An individual general taxpayer files six months at once and settles by deducting the tax paid under the preliminary notice.
VAT preliminary notice: who gets it and how much (50% of prior tax)
Individual general taxpayers and companies whose supply value in the prior taxable period was under KRW 150 million do not file a preliminary return. Instead, the tax office issues a notice for 50% of the tax paid in the prior taxable period. You pay the amount on the notice by the deadline. No notice is issued if the amount is under KRW 500,000.
The following individual business owners receive no notice. They have nothing to do in the preliminary period and file six months at once in the final return.
- You received a refund or otherwise had no tax payable in the prior taxable period
- You started the business during this preliminary period
- You changed from a simplified taxpayer to a general taxpayer
Even if you are subject to the preliminary notice, you can choose to file a preliminary return instead in the following cases. If you file a preliminary return, the notice you received is treated as void.
- Business was suspended or slow, and the supply value or tax payable for the preliminary period is less than one-third of the prior taxable period
- You want an early refund (for example, you have zero-rated sales such as exports, or equipment investment)
VAT for simplified taxpayers: once a year, January 25
A simplified taxpayer’s taxable period is January 1 to December 31. They file once, by January 25 of the next year. In July, a preliminary assessment of 50% of the tax paid in the prior taxable period is issued. However, a simplified taxpayer who issued tax invoices in the first half must file a preliminary return by July 25.
When the VAT deadline falls on a holiday: next business day (second half of 2026)
If a deadline falls on a Saturday, Sunday, or public holiday, the next business day becomes the deadline. For example, October 25, 2026 is a Sunday, so this second-half preliminary return is due by October 26 (Monday).
However, the second-half preliminary notice payment deadline for individual general taxpayers was extended by the National Tax Service to the end of October, because the October holidays may delay delivery of notices. October 31 is a Saturday, so the deadline is November 2 (Monday). Check the exact deadline on your notice or on Hometax.
Points that are easy to miss in VAT filing
- Allocation of common input tax: A business with both taxable and exempt activities must allocate input tax used in common, for example by the ratio of supply values. The amount allocated in the preliminary return is settled again in the final return based on the whole taxable period.
- Refunds in periods with large purchases: In periods with large purchases, such as new equipment or construction costs, a refund may arise. You can apply for an early refund in such cases, so it is wise to decide your filing method in advance to fit your cash schedule.
When you can do it yourself · When to hand it over
You can handle it yourself if
- All your sales and purchases are electronic tax invoices or card transactions that collect automatically on Hometax
- You are a simplified taxpayer who files once a year and your transactions are simple
Better to hand it over if
- You have a mix of cash sales, overseas sales, and paper tax invoices
- You have both taxable and exempt sales and must allocate common input tax
- You need help deciding whether to pay the preliminary notice or file a preliminary return
Barun Tax & Accounting handles individual and corporate VAT filing together with bookkeeping for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199