Korea Gift Tax Deduction Limits 2026: KRW 50 Million for Parent to Child, KRW 100 Million for Marriage or Birth
Gift tax deductions over 10 years combined are KRW 600 million from a spouse, KRW 50 million to an adult child, and KRW 20 million to a minor child. Marriage or birth adds KRW 100 million. File within 3 months from the end of the month you received the gift.
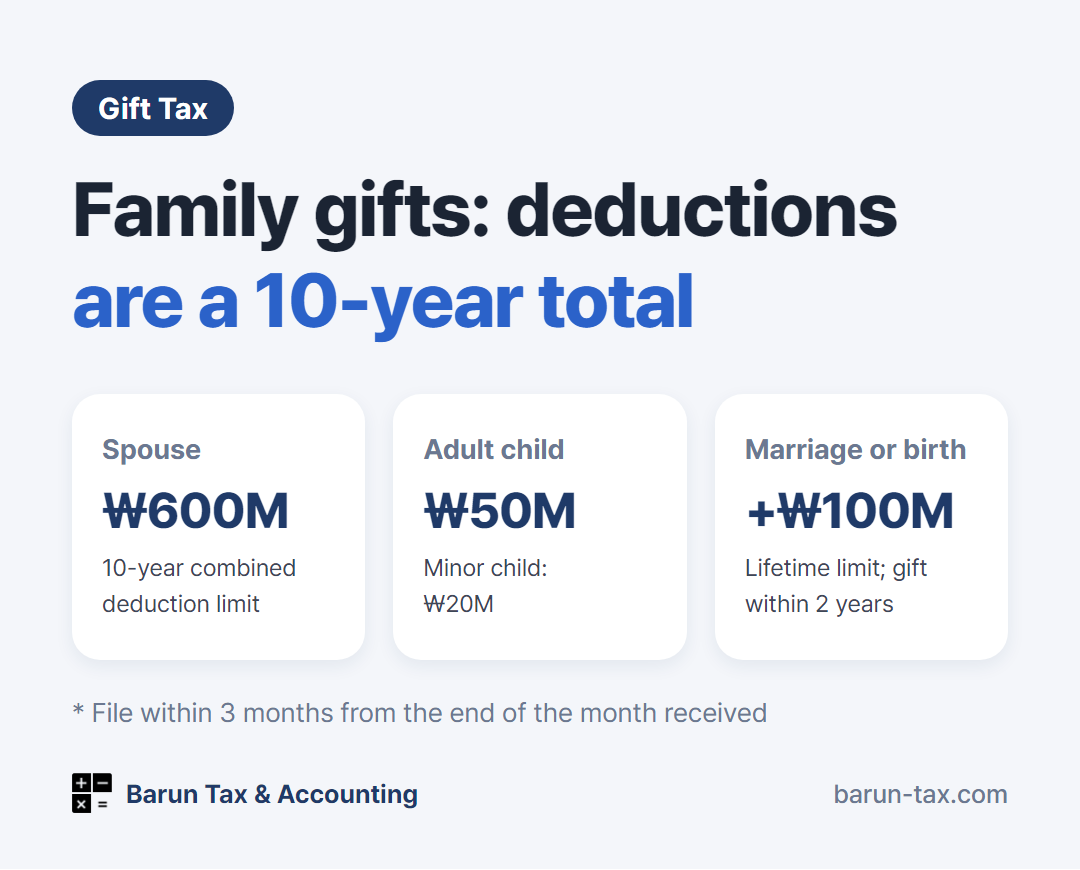
Gift tax is paid by the recipient. The deduction limits over 10 years combined are KRW 600 million from a spouse, KRW 50 million for an adult child or grandchild receiving from parents or grandparents, and KRW 20 million for a minor child or grandchild. For marriage or birth, KRW 100 million is added separately. File within 3 months from the end of the month you received the gift.
Gift tax deduction limits: gift deduction by relationship
Gift tax is paid by the recipient. Tax applies to the property received minus the deduction below. If the gift is within the deduction limit, there is no tax to pay.
| Giver → Recipient | Deduction limit (10 years combined) |
|---|---|
| Spouse | KRW 600 million |
| Parents or grandparents → adult child or grandchild | KRW 50 million |
| Parents or grandparents → minor child or grandchild | KRW 20 million |
| Child or grandchild → parents or grandparents | KRW 50 million |
| Other relatives (blood relatives within 6 degrees, in-laws within 4 degrees) | KRW 10 million |
Gift tax is aggregated over 10 years: the same group is counted together
The deduction limit applies not to a single gift but to the total received over 10 years. Amounts received from the same group are also counted together.
- Even if the father and mother each give KRW 50 million, the deduction is KRW 50 million in total. Parents and grandparents are all one group of “lineal ascendants.”
- If you give KRW 20 million when the child is young, and give KRW 50 million again after 10 years when the child is an adult, you can get the deduction both times. This is why people plan the timing of gifts over a long period.
Marriage and birth gift deduction: extra KRW 100 million
When a child marries or has a baby, property received from parents or grandparents can get an extra KRW 100 million deduction, separate from the KRW 50 million above.
- Marriage: gifts received within 2 years before or after the marriage registration date
- Birth: gifts received within 2 years from the child’s birth date (the adoption registration date for adoption)
- The lifetime limit for marriage and birth combined is KRW 100 million.
For example, if an adult child marries and receives KRW 150 million from parents, the regular KRW 50 million deduction plus the KRW 100 million marriage deduction may leave no gift tax. This requires that you had no gifts in the prior 10 years.
Gift tax filing deadline: 3 months from the end of the month received
File with the tax office for the recipient’s address within 3 months from the end of the month that includes the date you received the gift. If you file within the deadline, you get a 3% deduction of the calculated tax.
Even if there is no tax because the gift is within the deduction limit, it is wise to file. Later, when you buy a home or use a large sum, you may have to explain the source of the money. A gift tax filing record makes that explanation much easier.
Points that are easy to miss
- Bank transfers between family members can also be treated as gifts. Money spent as needed on living expenses or education is not subject to gift tax. But if the money is used to buy deposits, shares, or real estate, it is treated as a gift.
- If you lend money, write a loan agreement and keep records of actual interest and principal repayments, so that it is more easily accepted as a loan and not a gift.
- If you gift real estate, the recipient also pays acquisition tax. It is separate from gift tax, so calculate both together.
When you can do it yourself · When to hand it over
You can handle it yourself if
- It is a cash gift within the deduction limit, and you received no other gifts from the same group in the last 10 years
Better to hand it over if
- You are giving property that needs valuation, such as real estate or unlisted shares
- You received gifts several times, or from several people, within 10 years
- You want to use the marriage or birth deduction together with the basic deduction
- You are buying a home with gifted money and must document the source of funds
Barun Tax & Accounting handles gift tax filing and advance gift review for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199