Interim Income Tax Prepayment in Korea: Deadline, Who Pays, and Installments (2026)
The interim prepayment of comprehensive income tax is due November 30, 2026. The notice amount is one-half of the base amount for the preceding tax period. Covers who pays, estimate filing, and installments.
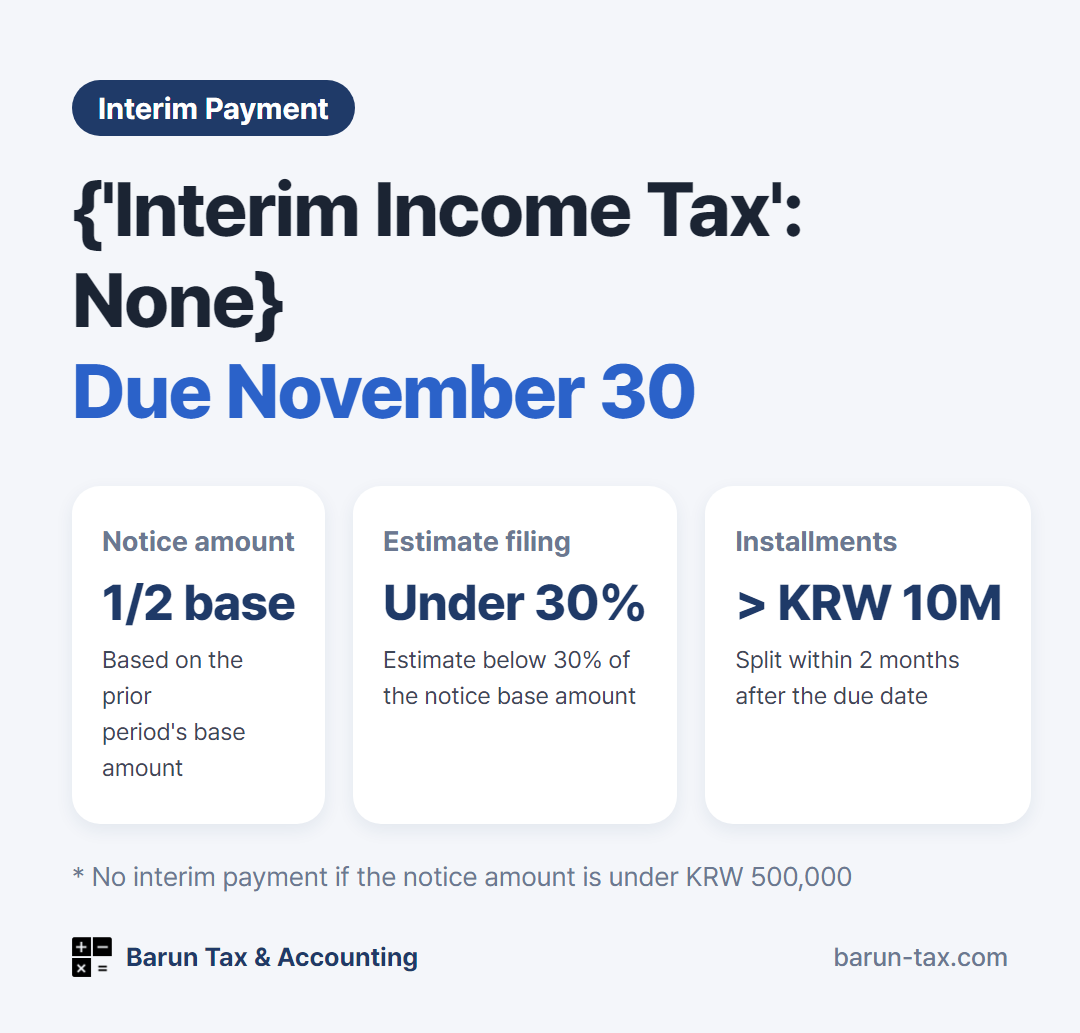
The interim prepayment of comprehensive income tax (종합소득세 중간예납) is due November 30, 2026. The notice amount is one-half of the interim prepayment base amount (중간예납기준액) for the preceding tax period. It applies to individuals with business income. If your first-half results fell this year, you can file an estimate. If the tax is over KRW 10 million, you can pay in installments.
What interim prepayment is: tax you pay early in November
Comprehensive income tax is finalized in May of the next year for the full year. But individuals with business income pay part of it early, in November. This is the interim prepayment. The amount you prepay is deducted from the determined tax at the final filing in May of the next year.
| Item | Details |
|---|---|
| Period covered | January 1 ~ June 30 |
| Notices mailed | Early November |
| Payment deadline | November 30 (a Monday in 2026) |
| Notice amount | One-half of the interim prepayment base amount for the preceding tax period |
Who does not make the interim prepayment
You do not make the interim prepayment in these cases.
- You started your business this year.
- You only have interest, dividend, salary, pension, or other income.
- The interim tax to be notified is under KRW 500,000.
Estimate filing: if your first half was weak
The notice amount is based on last year’s results. If your results fell sharply in the first half of this year, you may prepay more tax than you actually owe. In that case, you can file and pay an amount calculated from your actual January~June results (the estimated interim tax, 중간예납추계액).
- You can choose this if the estimate is less than 30% of the notice base amount.
- Once you file the estimate, the notice you received no longer applies. You pay the amount you filed.
- The estimate must be based on your first-half books. It helps to organize your first-half closing records before November.
Installments: over KRW 10 million, split over 2 months
If the tax due is over KRW 10 million, you can pay part of it in installments within 2 months after the deadline.
| Tax due | Amount you can pay in installments |
|---|---|
| Over KRW 10 million up to KRW 20 million | The part over KRW 10 million |
| Over KRW 20 million | Up to 50% of the tax |
Missing the deadline: what people overlook
- Missing the deadline adds a penalty tax (가산세). Even if you did not receive the notice, you can look up the notice on Hometax (홈택스) or the Sontax (손택스) mobile app. It is worth checking once during November.
- Paying the interim prepayment does not finish your May filing. In May, you file again based on the full year’s income. The interim tax you already paid is deducted.
When you can do it yourself · When to hand it over
You can handle it yourself if
- You pay the notice amount as printed, by the deadline.
- The amount is over KRW 10 million and you only need to apply for installments.
Better to hand it over if
- Your first-half results dropped sharply and you need to decide whether to file the estimate.
- You missed expenses or deductions when you filed in May.
Barun Tax & Accounting handles comprehensive income tax filing and interim prepayment estimate filing for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199