Korea One-Home Capital Gains Tax Exemption: Conditions (2 Years Held, KRW 1.2 Billion, Temporary 2 Homes)
The one-household one-home exemption requires holding the home for 2 years or more. If the area was a regulated area when you acquired it, you must also have lived there 2 years or more. Covers the KRW 1.2 billion limit and the temporary 2-home rule.
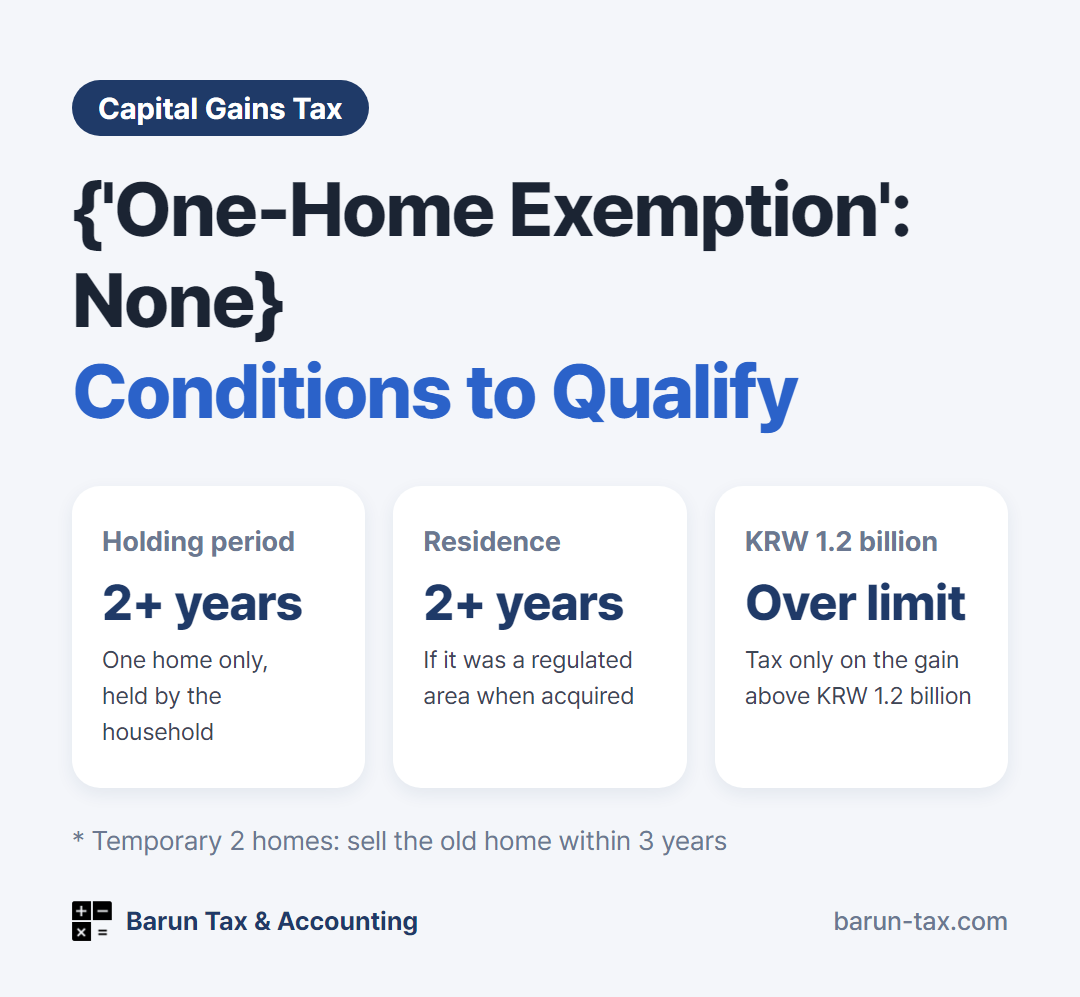
The one-household one-home capital gains tax (양도소득세) exemption applies when the household owns only one home in Korea and has held it for 2 years or more. If the area was a regulated area (조정대상지역) when you acquired the home, you must also have lived there for 2 years or more. If the sale price is over KRW 1.2 billion, tax applies to the part of the gain above that amount. If you temporarily own two homes because of a move, the temporary 2-home rule can still give you the exemption.
Basic conditions: 2 years held, 2 years lived in
When you sell a home, capital gains tax is exempt if you meet all of the following.
- The household owns only one home in Korea.
- You have held the home for 2 years or more.
- If the area was a regulated area when you acquired the home, you have lived there for 2 years or more.
A “household” includes the resident, the spouse, and family members who live at the same address and share living costs. A spouse counts as the same household even if living apart. Homes owned by children or parents who live with you also count toward the number of homes, so check them too.
The residence requirement is based on the time of acquisition
Whether the residence requirement applies depends on whether the area was a regulated area when you acquired the home, not when you sell.
- If it was not a regulated area when you acquired the home, 2 years of holding is enough even if the area is designated later.
- If it was a regulated area when you acquired the home, you need 2 years of residence even if the designation is lifted later.
Regulated areas often change with government real estate measures. It is best to check first whether the area was designated on the date you acquired the home.
Capital gains tax and the long-term holding deduction above KRW 1.2 billion
If the sale price is over KRW 1.2 billion, the whole gain is not exempt. Tax applies only to the part of the gain that corresponds to the amount over KRW 1.2 billion.
In this case, the long-term holding special deduction (장기보유특별공제) matters a great deal. For a one-household one-home, you can deduct 4% per year for the holding period and 4% per year for the residence period, up to 80% of the gain for 10 years or more. If you held the home but did not live in it, the deduction rate is much lower. So consider your residence period too.
Temporary 2 homes: owning two homes briefly while moving
If you buy a new home first and sell the old home later, you can still treat the old home as your only home and get the exemption if you meet the conditions below. This is called a temporary 2-home situation (일시적 2주택).
- You buy the new home at least 1 year after the date you acquired the old home.
- You sell the old home within 3 years of the date you acquired the new home.
- The old home meets the basic conditions above (2 years held, and 2 years lived in if needed).
Filing and holding period: what people overlook
- Some exempt sales still require a filing. For a home sold for more than KRW 1.2 billion, you must file a preliminary return within 2 months from the end of the month of sale.
- The holding period is counted from the balance payment date. It starts on the date you paid the balance (or the registration date, whichever is earlier), not the contract date.
- There are separate special rules for inherited homes, and for cases where you own two homes after marriage or after moving in with parents to care for them. If your situation is complex, get advice before you sell.
When you can do it yourself · When to hand it over
You can handle it yourself if
- You held one home for more than 2 years (and lived there 2 years if you acquired it in a regulated area), and the sale price is KRW 1.2 billion or less, so the exemption is clear.
Better to hand it over if
- The sale price is over KRW 1.2 billion.
- You temporarily own two homes because of a move, inheritance, or marriage.
- You are unsure about your holding or residence period, or whether the area was a regulated area when you acquired the home.
Barun Tax & Accounting handles capital gains tax filing and pre-sale tax review for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199