Korea Tax Invoice Deadline: Penalties for Late Issuance (2026)
The tax invoice deadline is the 10th of the month after the month of supply. Late issuance carries a 1% penalty on the supply value and no issuance carries 2%. Wrong invoices are fixed with a modified tax invoice.
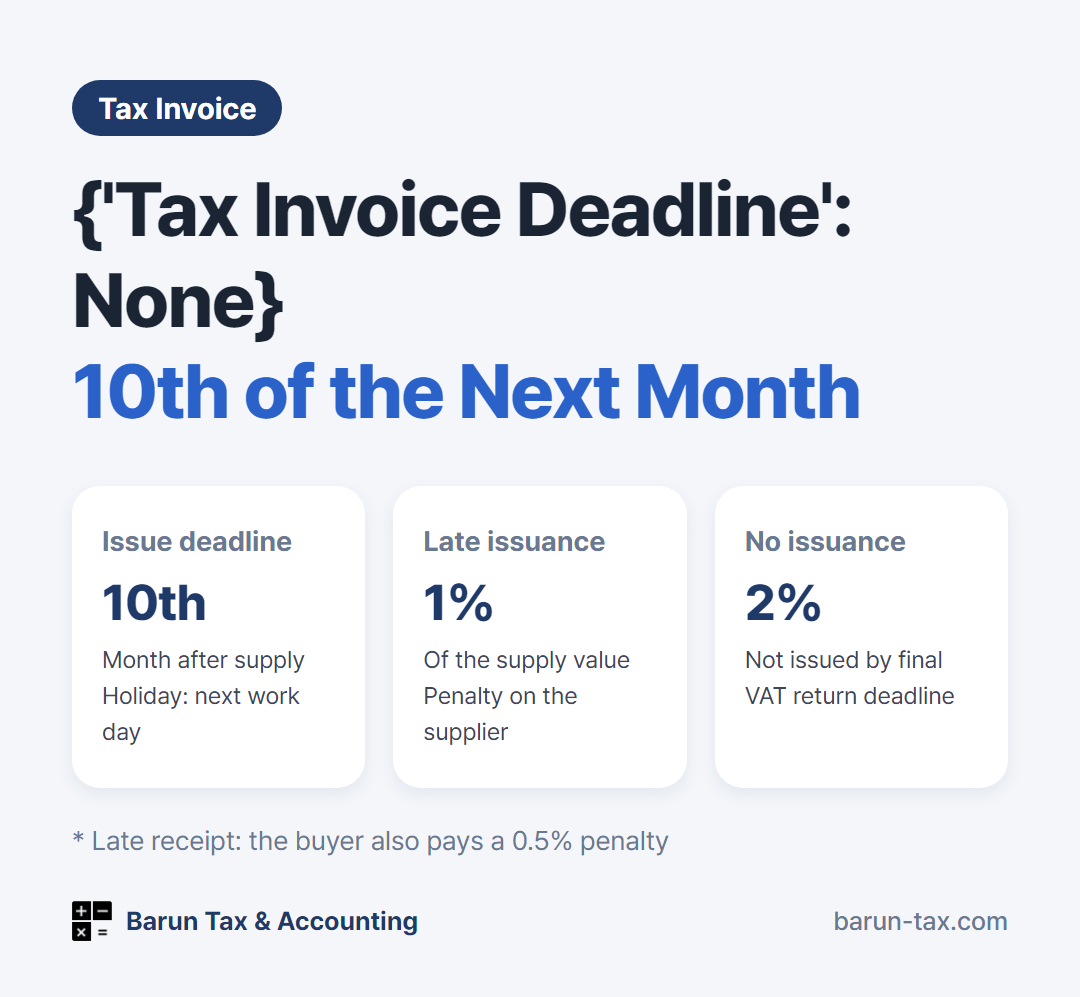
The tax invoice deadline is the 10th of the month after the month of supply. If you miss it, the supplier pays a penalty tax (가산세) of 1% of the supply value (2% if the invoice is not issued by the final VAT return deadline), and the buyer also pays a late receipt penalty. If you issued an invoice by mistake, you do not cancel it. You fix it with a modified tax invoice.
Tax invoice deadline: the 10th of the month after supply
In principle, you issue a tax invoice on the date you supply the goods or services. But you can combine a month of transactions into one invoice, dated the last day of the month and issued by the 10th of the next month.
| Item | Deadline |
|---|---|
| Issuing | The 10th of the month after the month of supply (next business day if a holiday) |
| Transmission to the National Tax Service (electronic) | The day after the issue date |
If you issue on Hometax (홈택스), the invoice is transmitted right away, so you do not need to worry about the transmission deadline. The month of the invoice’s preparation date decides the VAT filing period for that transaction, so the preparation date must match the actual date of supply.
Who must issue electronic tax invoices
Corporations, and individual business owners whose supply value (taxable plus exempt) per business place in the previous year was KRW 80 million or more, must issue electronic tax invoices. If a business that must issue electronically issues a paper invoice instead, a penalty of 1% of the supply value applies.
Late issuance penalties: both sides pay
| Case | Penalty |
|---|---|
| Late issuance (issued after the deadline but by the final VAT return deadline) | Supplier: 1% of the supply value |
| No issuance (not issued by the final VAT return deadline) | Supplier: 2% of the supply value |
| Late receipt | Buyer: 0.5% of the supply value |
If you issue late, the buyer also pays a penalty, so it is a burden for your customer too. Issuing an invoice in January for December transactions, backdated to December, is also late issuance if it is after January 10.
If you issued a wrong invoice: reasons and handling for a modified tax invoice
An electronic tax invoice cannot be canceled once issued. You fix it with a modified tax invoice. The preparation date and method depend on the reason.
| Reason | Handling |
|---|---|
| Contract cancellation | One negative (-) invoice dated the cancellation date |
| Change in supply value (discount, addition, etc.) | One invoice for the change only, dated the date of the change |
| Error in the entries (business registration number, amount, etc.) | One negative invoice and one correct invoice, both dated the original date |
| Double issuance by mistake | One negative invoice dated the original date |
For a contract cancellation or a change in supply value, the reason is dated when it occurred, so you do not need to correct a return you have already filed. For an error in the entries, you fix it as of the original date, so you may need to file an amended return if that period is already filed.
What people overlook
- Not receiving payment is not a reason for a modified tax invoice. If you cannot collect because a customer went bankrupt, for example, you handle it with the bad debt tax credit (대손세액공제).
- Issuing a modified tax invoice does not remove the original late issuance penalty. The best approach is to issue the correct invoice within the deadline in the first place.
- If the representative’s name or address is wrong but the business registration number is correct, the deduction is not affected. Correct it from the next invoice.
When you can do it yourself · When to hand it over
You can handle it yourself if
- You have only a few customers, and you issue a monthly total invoice on Hometax before the 10th of the next month.
Better to hand it over if
- You missed an invoice or issued a wrong one, and need to choose the right reason for a modified tax invoice.
- You have many customers or invoices, and need to match issued and received invoices to your books.
Barun Tax & Accounting handles tax invoice management and VAT filing for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199