Korea VAT: When Input Tax Cannot Be Deducted (Vehicles, Entertainment)
You cannot deduct input VAT without a tax invoice, or on entertainment expenses, non-business passenger cars (8 seats or fewer), and spending tied to exempt businesses or land. Also covers vehicles, card receipts, and pre-opening costs.
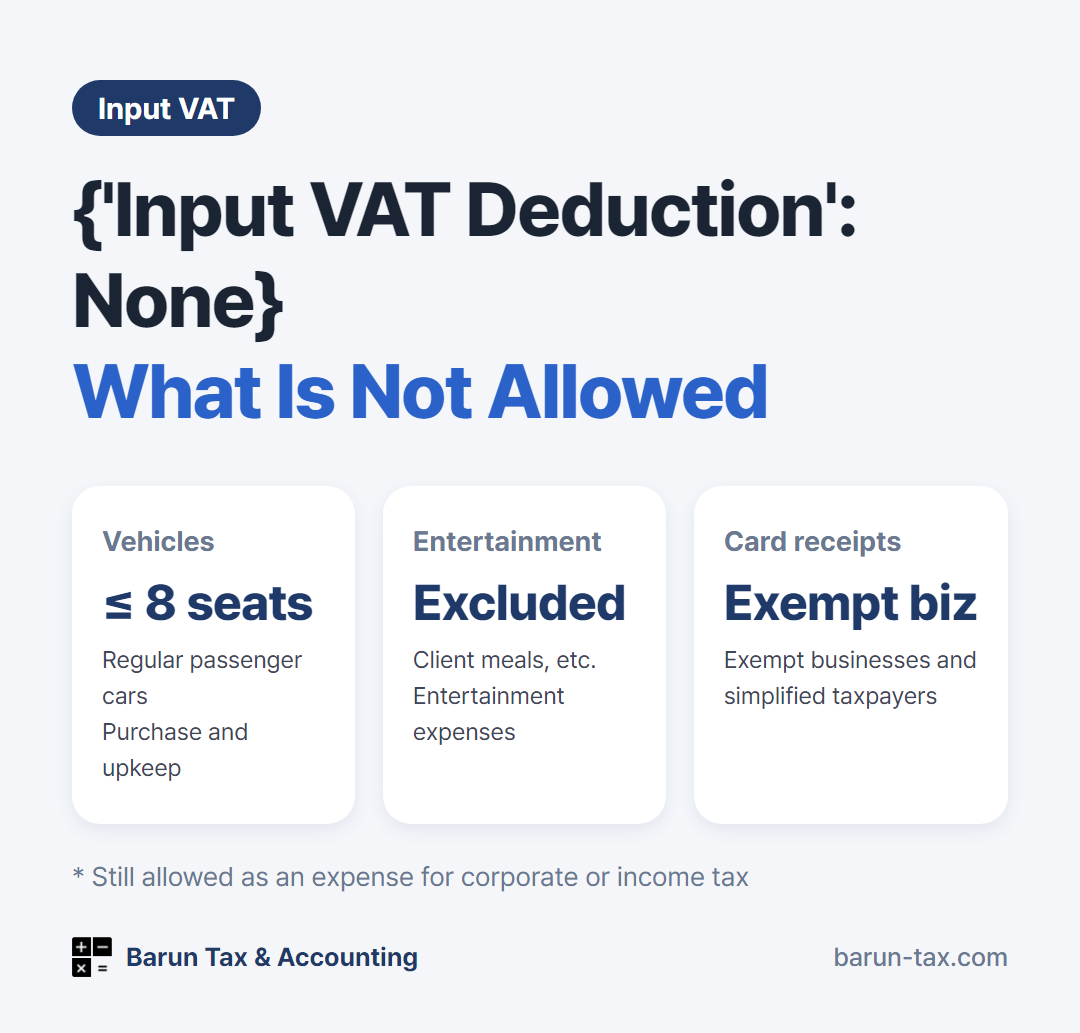
Even for business costs, you cannot deduct input VAT (매입세액) on spending with no tax invoice, entertainment expenses, regular passenger cars with 8 seats or fewer, or spending tied to an exempt business or land. Even if you paid by card, the VAT is often not deductible when the seller is an exempt business or a simplified taxpayer. If you deduct input VAT that you could not deduct, the tax is recovered later with a penalty tax (가산세).
When input VAT cannot be deducted: the basic rule
When you buy goods or services for your business, the VAT you pay (input VAT) is subtracted from your output VAT when you file. But in the cases below, you cannot deduct input VAT even if the spending was for business.
- You did not receive a tax invoice, or the tax invoice you received is missing required entries.
- The spending is not directly related to the business.
- The spending is for entertainment expenses (기업업무추진비).
- The cost is for buying, leasing, or maintaining a non-business passenger car.
- The spending is tied to an exempt business or to land.
Passenger car VAT deduction: it depends on the vehicle type
Vehicles cause the most confusion. For a regular passenger car, you cannot deduct input VAT on the purchase price, lease fees, rental fees, fuel, or repairs, even if you use it for work.
| Deductible | Not deductible |
|---|---|
| Compact cars (1,000cc or less) | Regular passenger cars with 8 seats or fewer (sedans, SUVs, etc.) |
| Cargo trucks, vans | Two-wheeled vehicles over 125cc |
| Vans seating 9 or more | |
| Two-wheeled vehicles of 125cc or less |
Businesses that use the vehicle itself in their operations, such as taxis, transport, and car sales, are an exception. Even if input VAT on a vehicle is not deductible, the cost is recognized as an expense for corporate tax and income tax within certain limits.
When you paid by card but cannot deduct input VAT
Even with a business card, whether you can deduct depends on who the seller is.
- Purchases from exempt businesses (hospitals, pharmacies, farm products, books, etc.) carry no VAT to begin with, so there is no tax to deduct.
- Card receipts from simplified taxpayers who cannot issue tax invoices (annual sales under KRW 48 million, etc.) are not deductible. You can check the other party’s tax type on the Hometax (홈택스) business status lookup.
- Overseas payments (overseas advertising, overseas software subscriptions, etc.) carry no Korean VAT, so there is no tax to deduct. You can still treat them as an expense.
Meals, phone bills, and pre-opening costs
- Employee meals and team dinners: deductible. But meals with clients are entertainment expenses and are not deductible.
- Meals the representative eats alone: it is hard to explain the link to the business, so they are generally not deducted.
- Mobile phone and internet bills: deductible if you receive a tax invoice in the business’s name. Bills paid by card in a personal name are hard to separate as business use, so deduction is difficult. It is best to ask your carrier to issue electronic tax invoices under your business registration number.
- Costs before opening: you can deduct them if you apply for business registration within 20 days after the end of the tax period that includes the purchase date. For start-up costs, get a tax invoice issued under the representative’s resident registration number if needed.
What people overlook
- If you deduct input VAT that you could not deduct, the tax is recovered later with a penalty tax. For unclear items, it is safer not to deduct.
- Separately from the VAT deduction, a cost used for the business can be recognized as an expense when calculating corporate tax or income tax. Do not throw away receipts just because the VAT is not deductible. Keep them.
When you can do it yourself · When to hand it over
You can handle it yourself if
- Your purchases are only on business cards and tax invoices, and you have no vehicle or entertainment spending.
Better to hand it over if
- Vehicle, entertainment, and pre-opening costs are mixed together.
- You have spending tied to an exempt business or to land.
- You need to sort card purchases one by one into deductible and non-deductible.
Barun Tax & Accounting handles VAT filing for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199