Missed the VAT Filing Deadline? Late Filing Penalty Reductions (2026)
If you miss the VAT filing deadline, file a late return. File within 1 month and the non-filing penalty (20%) is reduced by 50%. The deadline for the 2026 second-period preliminary VAT return is October 26.
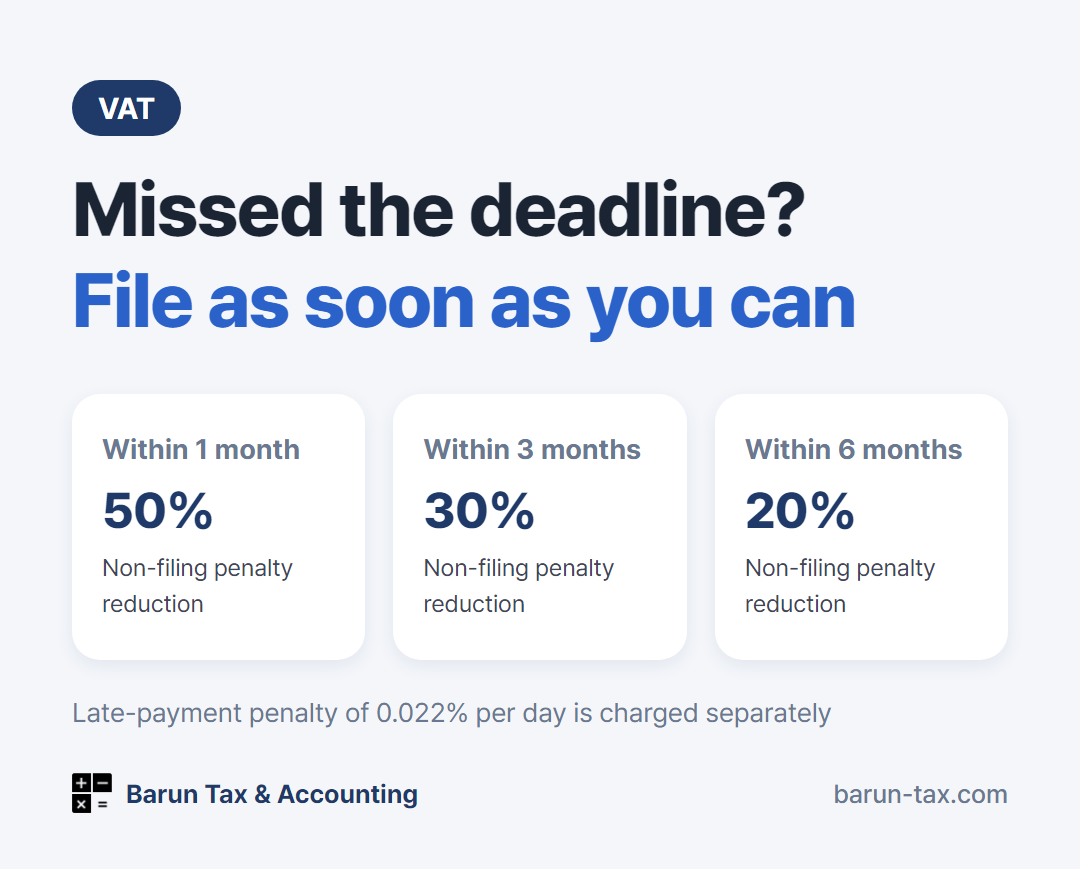
If you missed the VAT (부가가치세) filing deadline, file a late return (기한후신고). A non-filing penalty (20% of the tax due) applies, but it is reduced by 50% if you file within 1 month, 30% within 3 months, and 20% within 6 months. A late-payment penalty of 0.022% per day is also added for the days you paid late, so it is best to file and pay as soon as possible.
2026 Second-Period VAT Preliminary Return Deadline: October 26
October 25 is a Sunday, so the deadline for the second-period preliminary return (July~September) is Monday, October 26. Corporations file the preliminary return by this date. Individual general taxpayers do not file. They pay the amount on the notice. This year the National Tax Service extended the payment deadline for notices to Monday, November 2 (check the deadline printed on your notice). The full schedule is in VAT Filing Schedule at a Glance.
VAT Late Return: Non-Filing Penalty Reductions
If you did not file at all, file a late return. A non-filing penalty (20% of the tax due) applies, but the sooner you file, the more it is reduced.
| When you file the late return | Non-filing penalty reduction |
|---|---|
| Within 1 month | 50% |
| Over 1 month ~ within 3 months | 30% |
| Over 3 months ~ within 6 months | 20% |
A late-payment penalty (0.022% per day) is also added for the days you paid late. Once you realize the deadline has passed, it is best to file and pay as soon as possible.
If a corporation missed its preliminary return, another option is to skip the late return and report the amount together with the next final return (in January) as an omitted preliminary amount, calculating the penalties then. However, the longer the delay, the more late-payment penalty builds up, so it is worth comparing the amounts.
Filed, but Wrong: Amended Return and Refund Claim
| Situation | Method |
|---|---|
| You reported too little tax | Amended return (pay the additional tax) |
| You reported too much tax | Refund claim (request a refund, within 5 years of the statutory filing deadline) |
The underreporting penalty (10%) for reporting too little is also reduced the sooner you correct it.
| When you file the amended return | Underreporting penalty reduction |
|---|---|
| Within 1 month | 90% |
| Over 1 month ~ within 3 months | 75% |
| Over 3 months ~ within 6 months | 50% |
| Over 6 months ~ within 1 year | 30% |
Points That Are Easy to Miss
- Penalties apply only to additional tax you owe. If the correction increases the refund you receive, no late-payment penalty applies.
- You cannot put a deduction you missed in a past period into your next return instead. You must correct that period with an amended return or a refund claim.
- If you issued or received a tax invoice late, tax invoice penalties may apply separately from the filing penalties. See Tax Invoice Issuance Deadline.
When you can do it yourself · When to hand it over
You can handle it yourself if
- Your transactions are simple, and it has been less than 1 month since you missed the deadline, so you can file a late return right away.
Better to hand it over if
- You missed more than one period.
- The return you filed was wrong, and you need an amended return or a refund claim.
- You need the penalties and reduction rates calculated.
Barun Tax & Accounting handles late VAT returns, amended returns, and refund claims for foreign residents and foreign-owned companies. We reply to emails within one business day. contact@barun-tax.com · KakaoTalk · +82-10-2701-6199